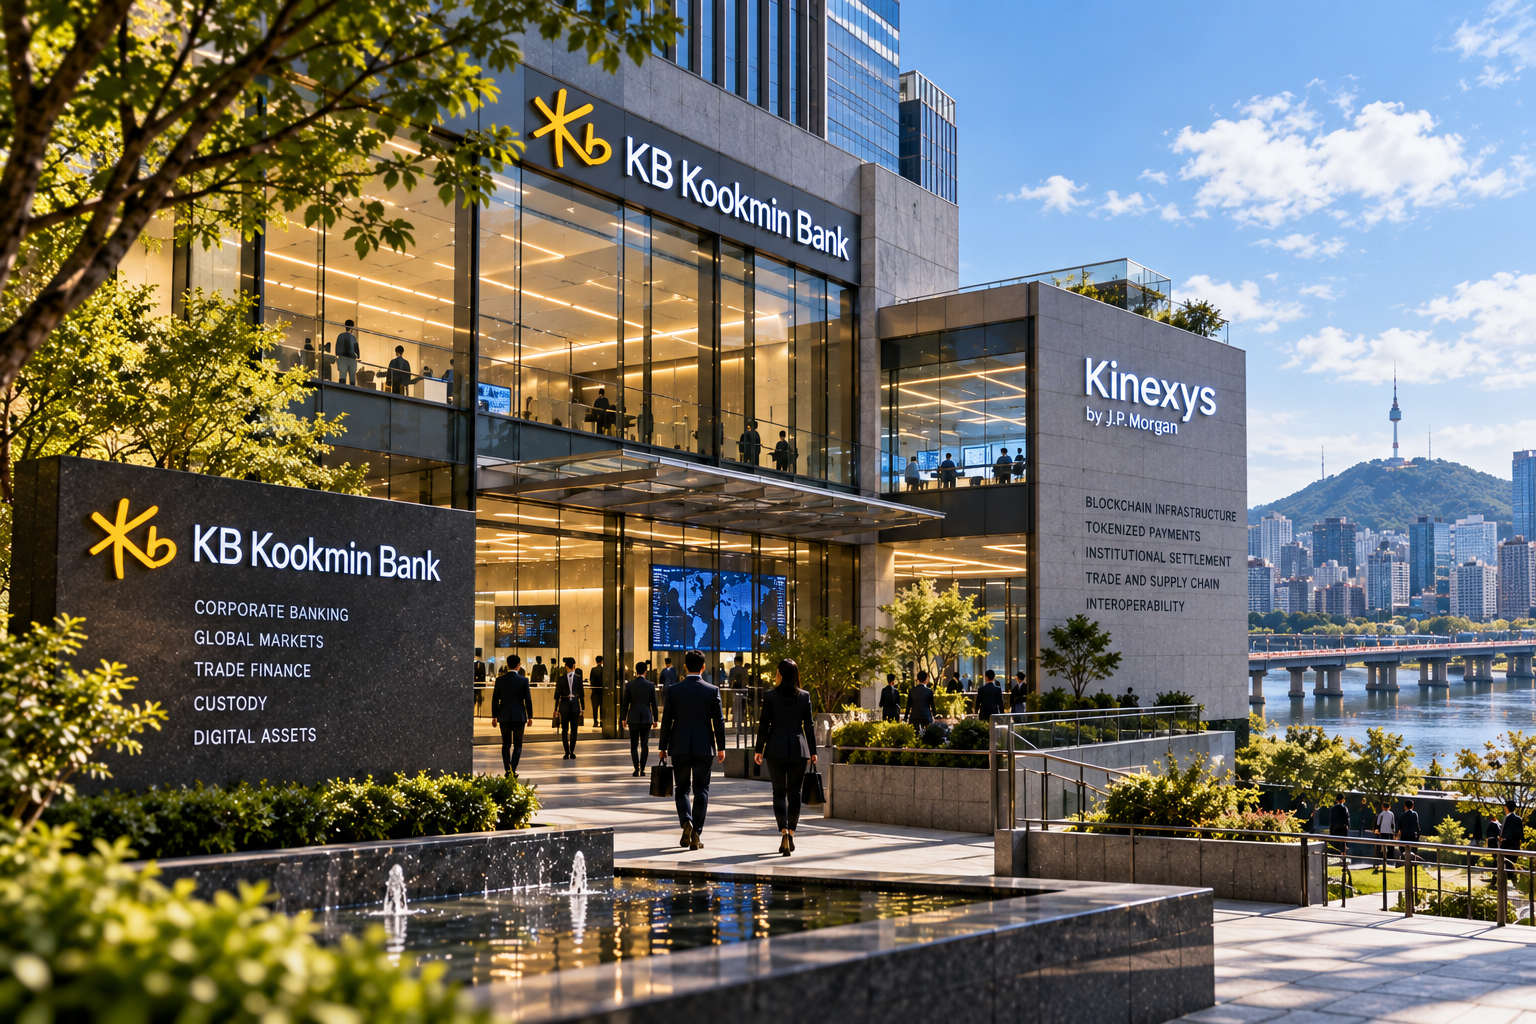
KB Kookmin Bank is introducing an import and export corporate payment service using the Blockchain Deposit Account network operated by Kinexys by J.P. Morgan.
J.P. Morgan says KB Kookmin is the first Korean financial institution to use the network for this type of payment service.
The service is intended to be available through KB Kookmin’s domestic branches in Korea and its Singapore branch.
Kinexys says its blockchain infrastructure processes an average of approximately $7 billion per day and has handled more than $4 trillion in cumulative transactions since inception.
The relevant part is the workflow being connected.
Import and export payments already involve regulated bank money, treasury decisions, foreign exchange, counterparties and reconciliation.
The objective is therefore not to create a new asset for corporate clients.
It is to change how commercial bank money moves inside an existing business process.
That distinction matters because corporate treasury departments generally do not need another token to manage.
They need payments to arrive when expected, cash positions to remain visible and funding to be available without unnecessary operational friction.
A blockchain based deposit network can be useful if it improves those functions while remaining integrated with the bank accounts and controls companies already use.
Kinexys also differs from many early institutional blockchain projects because the network already reports meaningful transaction activity.
That does not prove the KB Kookmin service will immediately generate large volumes.
It does mean the underlying infrastructure is not being introduced solely for this pilot or announcement.
The more interesting question is how the Korean bank incorporates that infrastructure into normal client payment operations.
What to watch
Actual corporate use will matter more than the first connection.
Transaction volumes, supported currencies, branch usage and the number of clients using the service for recurring trade flows will provide better evidence of adoption.
The longer term value will depend on whether clients experience the Kinexys route as part of ordinary banking rather than as a separate digital asset process.
That is usually where institutional infrastructure becomes useful: when the technology disappears into the workflow.